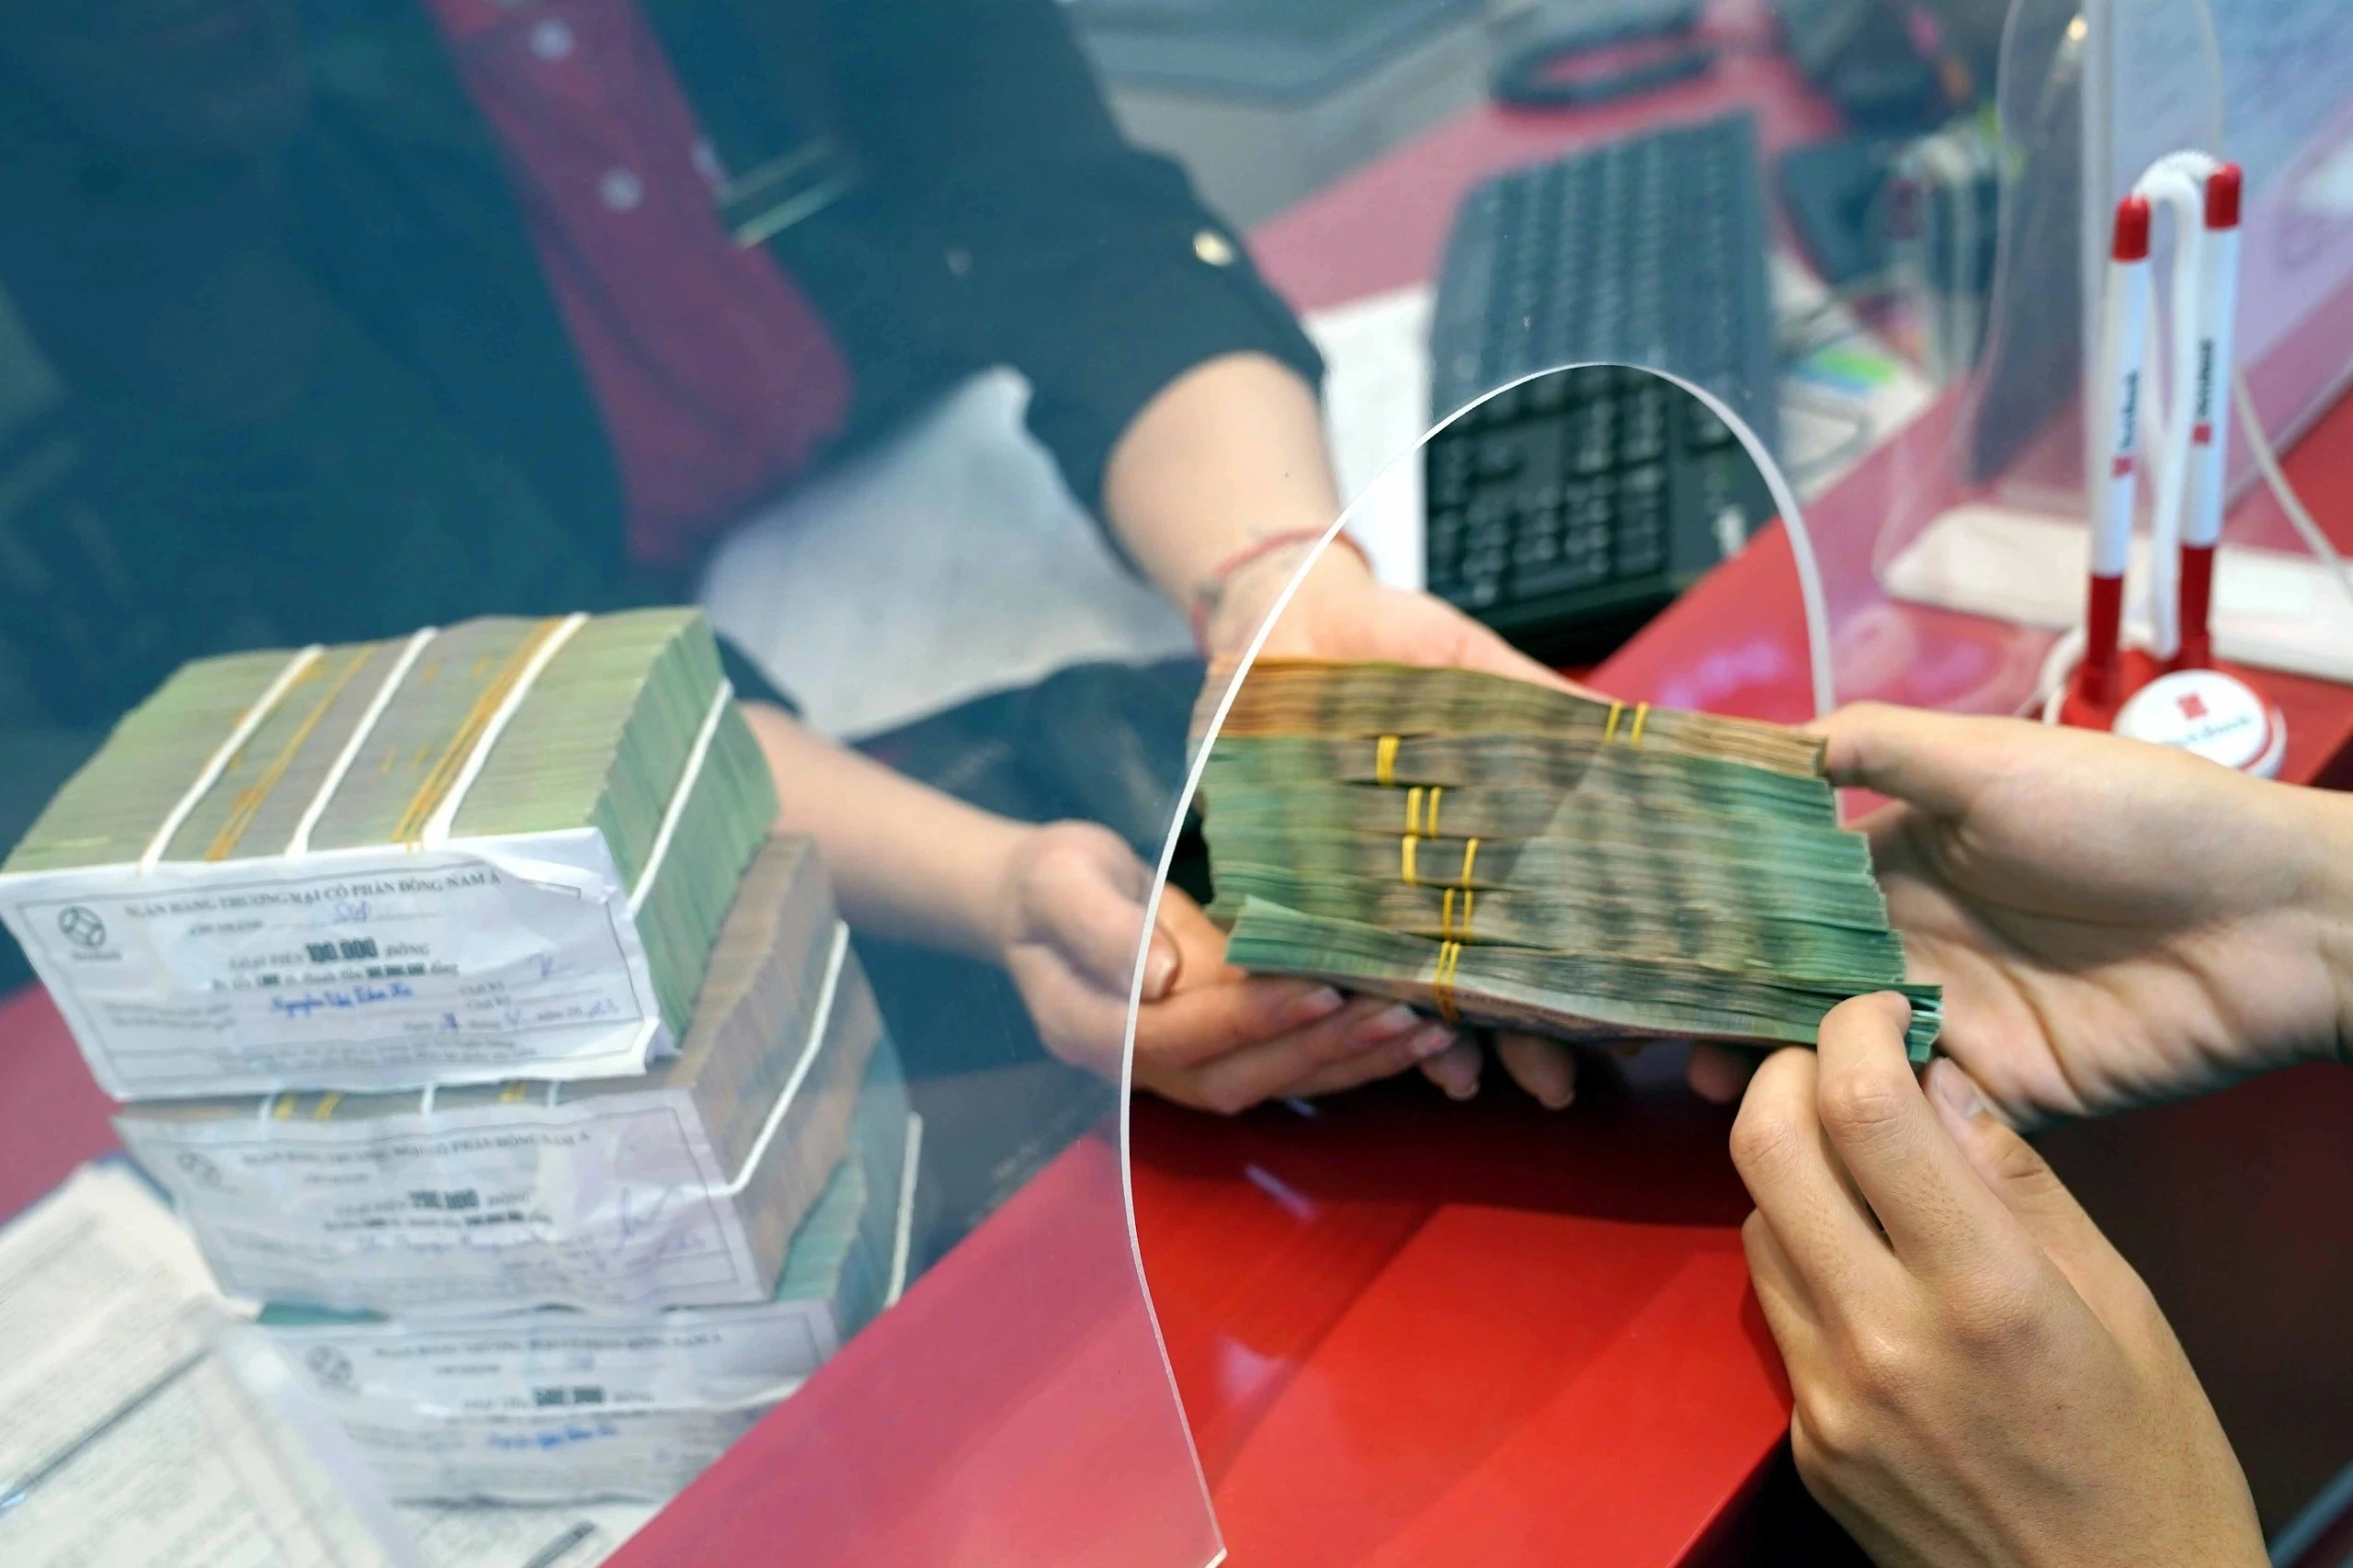
Vietnam’s banking sector is seeing a clear split this month. Deposit rates are climbing, sometimes sharply, while lending rates stay largely stuck despite pressure from the central bank to bring them down.
Savings Deposit Rates
Banks are competing hard for deposits. Publicly listed rates top out just under 8% a year, and most commercial banks have nudged rates upward. Once bonus margins or promotions are added, effective yields on 12 month deposits of 50 million to 500 million dong can reach 9.6% a year. For very large deposits, from 50 billion dong and up, Bac A Bank offers 7.3% a year, while some foreign banks go as high as 8.6%. Six to twelve month terms are expected to stay above 7% a year.
A smaller group, close to 10 banks, is quietly offering 9% a year or more even on deposits of just a few hundred million dong, usually through informal staff arrangements or special promotions rather than published rates. Certificates of deposit are also paying up to 9% a year on six month terms, well above ordinary savings accounts. Some banks sweeten the deal further by paying interest upfront at the start of the term, and non-bank financial platforms are advertising accumulated yields of up to 14% a year, though these sit outside the regulated banking system.
Home Loan Rates
Mortgage lending is the one area where rates are actually easing. Promotional fixed rates for home loans start from around 5% a year under programs such as An Cu Vung Buoc or Ngoi Nha Dau Tien, both aimed at first time buyers. Banks are shaving off an extra 0.2 percentage points for new customers, priority clients, or borrowers who receive their salary through the bank.
Consumer and Business Loans
Outside the housing sector, banks continue to run short term promotional packages for both consumer loans and business financing, but broad based cuts remain limited. BIDV, for example, has rolled out a 200 trillion dong credit package aimed at production and business activity. These offers tend to be targeted and temporary rather than a general lowering of the loan market.
Floating Rate Loans
No specific monthly figures for floating rates were available this month. But the direction is fairly predictable. Floating rates are typically set as a base or deposit rate plus a fixed margin, so as deposit costs climb toward 7% to 9.6% a year, floating rates are likely to stay relatively high once initial promotional periods expire, as banks work to protect their profit margins.
Bottom line: deposit rates are rising to attract capital, mortgage rates are easing modestly to support homebuyers, and broader lending rates, especially floating ones, face limited room to fall given elevated funding costs.
>> Vietnam Interest Rates in July 2026: Lending Rates Remain High Despite Expectations of Future Cuts